

Traditional loan guidelines don’t reflect every borrower’s income, assets, or goals. Waterstone Mortgage offers flexible financing options, including non-QM loans, for qualified homebuyers and investors with a wide range of financial situations.
Mortgage qualification is not one-size-fits-all. A salaried employee with predictable W-2 income may fit comfortably within traditional mortgage guidelines — but a business owner, real estate investor, medical professional, or high-net-worth borrower may have an equally strong financial profile that simply looks different on paper.
This is where non-qualified mortgage, or non-QM, loans can help. These programs give lenders additional ways to evaluate income, assets, cash flow, and other factors when standard documentation does not reflect a borrower’s full financial picture.
In a market where affordability and available cash can shape every decision, access to a broader range of financing options can make a meaningful difference for your homeownership journey.
What a Non-QM Loan Means
A qualified mortgage, commonly called a QM loan, must meet specific federal standards. A non-QM loan falls outside one or more of those specific standards, but it is not a no-documentation loan, and it does not eliminate responsible underwriting. Lenders must follow applicable ability-to-repay requirements and evaluate whether the borrower can repay the mortgage.
The key difference is flexibility. Depending on the program, a lender may be able to consider bank statements, eligible assets, or a property’s rental cash flow instead of relying only on the documentation used for a traditional mortgage. This can create options for qualified borrowers whose finances are sound but do not fit a standard template.
Why Lending Flexibility Matters in a Challenging Market
A challenging housing market can put more pressure on a buyer’s budget and cash reserves. Higher home prices, changing interest rates, and competition for desirable properties may require borrowers to consider how much cash they want to use at closing and how a loan fits their larger financial plan.
Some lenders offer a limited menu of mortgage products. So, if a borrower does not meet the requirements for those products, the conversation may end too soon. A lender with non-QM and specialized programs can examine the borrower’s situation from more than one angle and compare available options. That breadth is especially valuable when a borrower has non-traditional income, substantial assets, multiple financed properties, or career-specific financial circumstances.
Non-QM financing is not automatically the right choice for every borrower. Rates, fees, down payment requirements, reserve requirements, and documentation standards may differ from those of traditional loans. A mortgage professional can explain the trade-offs and help determine whether the added flexibility supports the borrower’s goals.
Flexible Mortgage Programs from Waterstone Mortgage
At Waterstone Mortgage, we offer a range of non-QM and specialized mortgage options for borrowers whose needs may not be fully served by conventional financing. Program availability, terms, and eligibility requirements vary, so the right starting point is often a review of the borrower’s complete financial picture.
To help you gain an understanding of which loan programs may fit unique scenarios, take a look at these scenarios and possible loan solutions…
Asset Amplify
Situation: “I have assets, but my monthly income is difficult to document.”
Possible solution: Asset Amplify is designed for borrowers who have significant eligible assets but whose income does not fit traditional lending guidelines. Rather than requiring borrowers to liquidate those assets or pledge them as collateral, the program may use assets such as savings and investments to help calculate qualifying income. Eligible borrowers may also combine asset-based income with other income sources.
Details:
- Up to 90% financing available
- Loan amounts up to $2 million, with higher amounts available in select cases
- Interest-only option available*
Statement Select
Situation: “My tax returns don’t reflect what my business earns.”
Possible solution: Business owners, freelancers, entrepreneurs, and other independent earners may have strong cash flow even when their tax returns or W-2 forms do not tell the full story. Statement Select offers alternative income documentation options that can better reflect how these borrowers earn and manage money.
Details:
- 12- or 24-month personal or business bank statement options
- 1099-only and profit-and-loss statement options available
- Up to 90% financing with no mortgage insurance, subject to program requirements
- Loan amounts up to $3 million
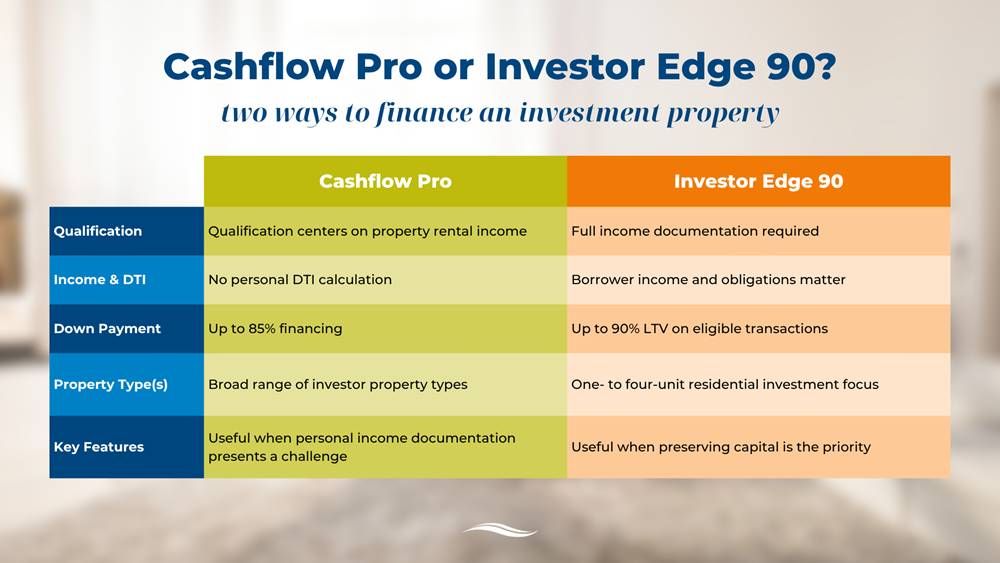
Cashflow Pro for Investors
Situation: “I want my rental property’s income to qualify.”
Possible solution: Cashflow Pro is a debt service coverage ratio, or DSCR, program for real estate investors. Instead of qualifying through personal income documents and a traditional debt-to-income calculation, eligible borrowers may qualify based on the investment property’s rental income relative to its monthly housing expense.
Details:
- No personal income, employment, or debt-to-income calculation on eligible investment purchases or refinances
- Loan amounts up to $3 million
- Up to 85% financing with no mortgage insurance
- Options for several property types and investment strategies
Investor Edge 90
Situation: “I want to preserve capital when buying an investment property.”
Possible solution: Investor Edge 90 is a full-documentation investment property program for qualified investors who want to expand their portfolios while limiting the amount of capital tied up in a purchase. The program can also accommodate investors with larger portfolios and several residential property types.
Details:
- Up to 90% loan-to-value for loan amounts up to $1.5 million
- Up to 85% loan-to-value for two- to four-unit properties
- No mortgage insurance
- Available to investors with up to 50 financed properties
- Interest-only option available*
- Eligible properties include attached and detached single-family homes, two- to four-unit properties, planned unit developments, warrantable condominiums, and rural properties
Investor Edge 90 is a full-documentation program for investment properties. Buyers who need rental income to qualify must own a primary residence.
Medical Professional Program
Situation: “I am beginning or advancing my medical career.”
Possible solution: Medical professionals can have high earning potential while also carrying significant student loan debt or could be preparing to begin a new position. Our Medical Professional Program accounts for several of these career-specific circumstances and is available to eligible medical professionals, including qualifying physicians, dentists, veterinarians, pharmacists, nurse practitioners, and certified registered nurse anesthetists.**
Details:
- Up to 100% financing with no mortgage insurance on qualifying loan amounts up to $2 million
- Student loan debt may be excluded from the debt-to-income calculation in qualifying circumstances
- Employment may begin up to 150 days after the note date
- Newly hired contractors and 1099 employees may be eligible
Choosing the Right Loan Starts with the Right Questions
The value of a broad loan portfolio is not simply the number of programs available — it’s the ability to identify which program, if any, aligns with a borrower’s income, assets, property, cash needs, and long-term plans. Two borrowers purchasing similar homes may need very different financing strategies.
If you’re considering buying a home or an investment property, when comparing lenders, you may want to ask:
- Do you offer options for self-employed borrowers or applicants with non-traditional income?
- Can eligible assets or investment-property cash flow be considered for qualification?
- What down payment, reserve, credit, and documentation requirements apply?
- How do the rate, fees, and total monthly payment compare with other available options?
- If the loan includes an interest-only period, when will the payment change and what could the new payment be?
Explore More Ways to Finance Your Goals
A traditional mortgage works well for many borrowers, but it’s not the only path. That’s why it’s important for homebuyers to work with a lender that offers a wide range of loan programs with flexible guidelines that can accommodate a variety of financial situations.
Our non-QM and specialized loan programs give qualified homebuyers and investors more ways to present their financial strengths and pursue their goals.
So, let’s get started! Connect with a local Waterstone Mortgage loan originator to discuss your situation and compare the financing options that may be available to you.
All loan requests are subject to credit approval and specific loan program requirements and guidelines. Program availability, terms, and geographic restrictions may apply. Program features may change. Contact a Waterstone Mortgage loan originator for current details.
Some program features may be available through a broker relationship with other lenders. Waterstone Mortgage is not affiliated with those lenders. Credit approval is at the sole discretion of the lender.
*The interest-only option allows borrowers to make minimum interest payments for a set period. When the interest-only period ends, the monthly payment is recalculated to include principal and interest payments for the remaining loan term, which will increase the monthly payment.
**Eligible professions include: Medical Doctor (MD), Doctor of Osteopathy (DO), Doctor of Dental Science or Surgery (DDS), Doctor of Dental Medicine (DMD), Doctor of Ophthalmology (MD or DO), Doctor of Psychiatry (MD or DO), Doctor of Pharmacy (PharmD), Doctor of Veterinary Medicine (DVM/VMD), Doctor of Podiatric Medicine (DPM), Certified Registered Nurse Anesthetist (CRNA), Nurse Practitioner (NP) with Master of Science in Nursing (MSN) or Doctor of Nursing Practice (DNP), medical residents, fellows, or interns with one of the above degrees.